Documents to Bring to a Car Dealership: What You Need to Buy a Car
Bring a photo ID, proof of insurance and a way to pay. Financing adds pay stubs and proof of address. Trading in adds your title or payoff quote and every key.
By Vitaliy Kuznetsov · Updated Sep 25, 2026 · 6 min read
To buy a car from a dealership, bring a photo ID, proof of auto insurance and a way to pay: a cashier's check, a personal check, a debit card or a pre-approval letter. Financing through the dealer adds your two most recent pay stubs and proof of address. A trade-in adds the title (or your lender's payoff details), the registration and every key.
What to bring
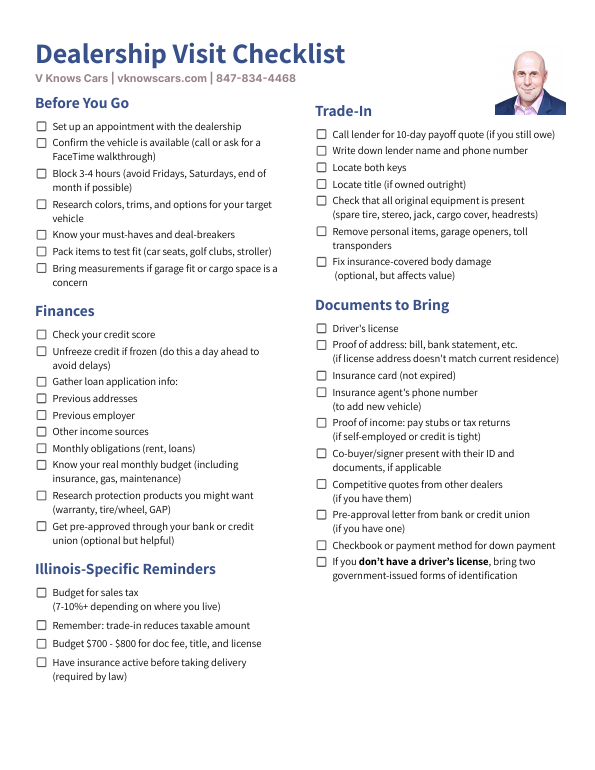 Download the checklist (PDF)Estimate your out-the-door price before you go
On this page
What to bring, by situation
| Situation | Bring |
|---|---|
| Every buyer | Unexpired photo ID, proof of insurance (or your agent's number), your payment method, your current address. |
| Dealer financing | Two recent pay stubs (self-employed: tax returns), proof of address, your Social Security number, a co-signer with ID if one is needed. |
| Bank or credit union loan | The pre-approval letter and the lender's name and contact, so the dealer can list the lien. |
| Paying cash | Cashier's check or wire confirmation. The dealer reports cash over $10,000 to the IRS and needs your SSN. Cashier's checks of $10,000 or less count as cash for that rule. |
| Leasing | Same as financing. Lessors often require higher insurance limits, so ask your agent first. |
| Trade-in you own | Title, registration, every key and fob. Every name on the title signs, or bring a power of attorney. |
| Trade-in with a loan | Lender name, account number and a 10-day payoff quote. No paper title? Your lender may hold an electronic one. |
| First car, no credit | The everyone list, proof of income and address, a larger down payment and often a co-signer. |
| Business or LLC | EIN, formation documents, proof the signer can bind the company, and your personal ID. |
The three things everyone needs
1. A valid photo ID
A driver's license is the standard. Without one, bring two forms of government-issued ID, such as a state ID card and a passport. Everything has to be unexpired. Anyone signing the paperwork, including a co-buyer, needs their own.
2. Proof of auto insurance
Every state requires liability coverage (Illinois minimums are 25/50/20) before you drive the car. The dealer will want proof that covers the new car, which means its VIN. Your agent can add the car over the phone once you give them the VIN, and email you the new card. If you have never insured a car, get a quote before you shop.
3. A way to pay
Bring a cashier's check, a personal check, a debit card or a pre-approval letter for the down payment. Dealers do take personal checks, but they may call your bank to confirm the funds or wait for the check to clear before releasing your plates. Ask the dealer about limits on card payments. Wire transfers can't go through after banking hours or on weekends.
If you're financing or leasing
Lenders verify your identity, income and address:
- Two recent pay stubs showing year-to-date income. Self-employed buyers usually need two years of tax returns.
- Proof of address such as a utility bill or bank statement, mainly if the address on your ID is out of date.
- Your Social Security number for the credit check. You need to know the number; the card itself is rarely needed.
- Loan application details: previous addresses, employer history, other income and monthly obligations like rent.
A pre-approval from your bank or credit union gives you a rate to compare against the dealer's offer. Before you sign, run the numbers in the out-the-door price calculator so you can compare the total price as well as the monthly payment.
If you're trading in
- Title if you own the car outright. If you still owe money, call your lender for a 10-day payoff quote and write down the lender's name, phone and your account number.
- Registration for the car you're trading.
- Every key and fob. A missing key can lower the trade offer.
- Everyone on the title. If a co-owner can't be there, ask the dealer about a power of attorney before you go.
In Illinois you're taxed on the price minus your trade-in value, and there has been no cap on that credit since January 1, 2022.
Common paperwork delays
Small mismatches in the paperwork can slow a deal down:
- Names that don't match. Your ID, credit application, insurance and title should show the same name, down to the middle initial.
- Insurance that doesn't cover the new car yet. Agents may be closed in the evening or on Sunday, so call before you head in.
- The lender wants more after approval. A conditional approval can come back asking for pay stubs or proof of address. Bringing them saves a second trip.
- An unconfirmed payoff. Lenders are often closed on weekends, so get the payoff quote a few days ahead.
- An absent co-owner or co-signer. They usually need to sign in person.
Special situations
First-time buyer or no credit
Lenders will look closely at income and residence. Bring extra pay stubs and a bank statement. A co-signer, if you have one, should bring their own ID and proof of income. A larger down payment helps.
No driver's license
You can buy and register a car without one. Bring two forms of government-issued ID, such as a state ID and a passport, arrange for a licensed driver to test drive it and bring it home, and check that your insurer will cover it.
Recently moved
If the address on your ID is out of date, bring two documents showing the new one, like a lease and a utility bill. Lenders are the ones who usually ask.
If you're buying in Illinois
- Tax: vehicle sales tax runs from 6.25% statewide to about 10.25% in Chicago. Your out-the-door estimate shows it for your ZIP.
- Fees: the dealer files your title and registration. See what the ERT fee is and whether it's optional.
- Temporary registration: a temporary registration permit is good for up to 90 days while your plates and title are processed.
- Emissions: testing depends on your ZIP code, and newer cars are exempt for their first few model years. Check the Illinois EPA lookup for a used car.
- Bought out of state: Illinois residents file Form RUT-25 and get credit for tax already paid to the other state.
- Under 18: the title application generally needs a parent or guardian's signed consent, and lenders require buyers to be 18. Check with the Secretary of State.
FAQ
What ID do you need to buy a car?
A valid driver's license. Without one, bring two forms of government-issued ID, such as a state ID card and a passport. The dealer needs it for the paperwork, financing and insurance.
Do you need proof of insurance to buy a car?
You need coverage before you drive it off the lot. Most dealers ask for proof at signing. Your agent can add the new car by phone if you give them the VIN.
Do you need a driver's license to buy a car?
No, but you'll need two forms of government-issued ID, such as a state ID and a passport, and a licensed driver to drive it home.
Can I buy a car without pay stubs?
Sometimes. Self-employed and cash buyers use tax returns or bank statements, and paying cash needs no income proof at all. Lenders decide for financed deals.
Do I need my Social Security card?
Usually not. Lenders need the number for the credit check, and the IRS requires it for cash over $10,000, but the card itself is rarely needed.
How old do you have to be to buy a car?
18 in practice. Lenders require it, and buyers under 18 generally need a parent or guardian.
Sources
Written by V (Vitaliy Kuznetsov)
I've sold cars, run a 3,000-person shopper community and led product at Cars.com. More about me or call or text 847-834-4468 and I'll help with your purchase.